Loans 

Credit Card
IndiaLends App is available in
Loan Against Mutual Funds vs Personal Loan: Which Is Cheaper?
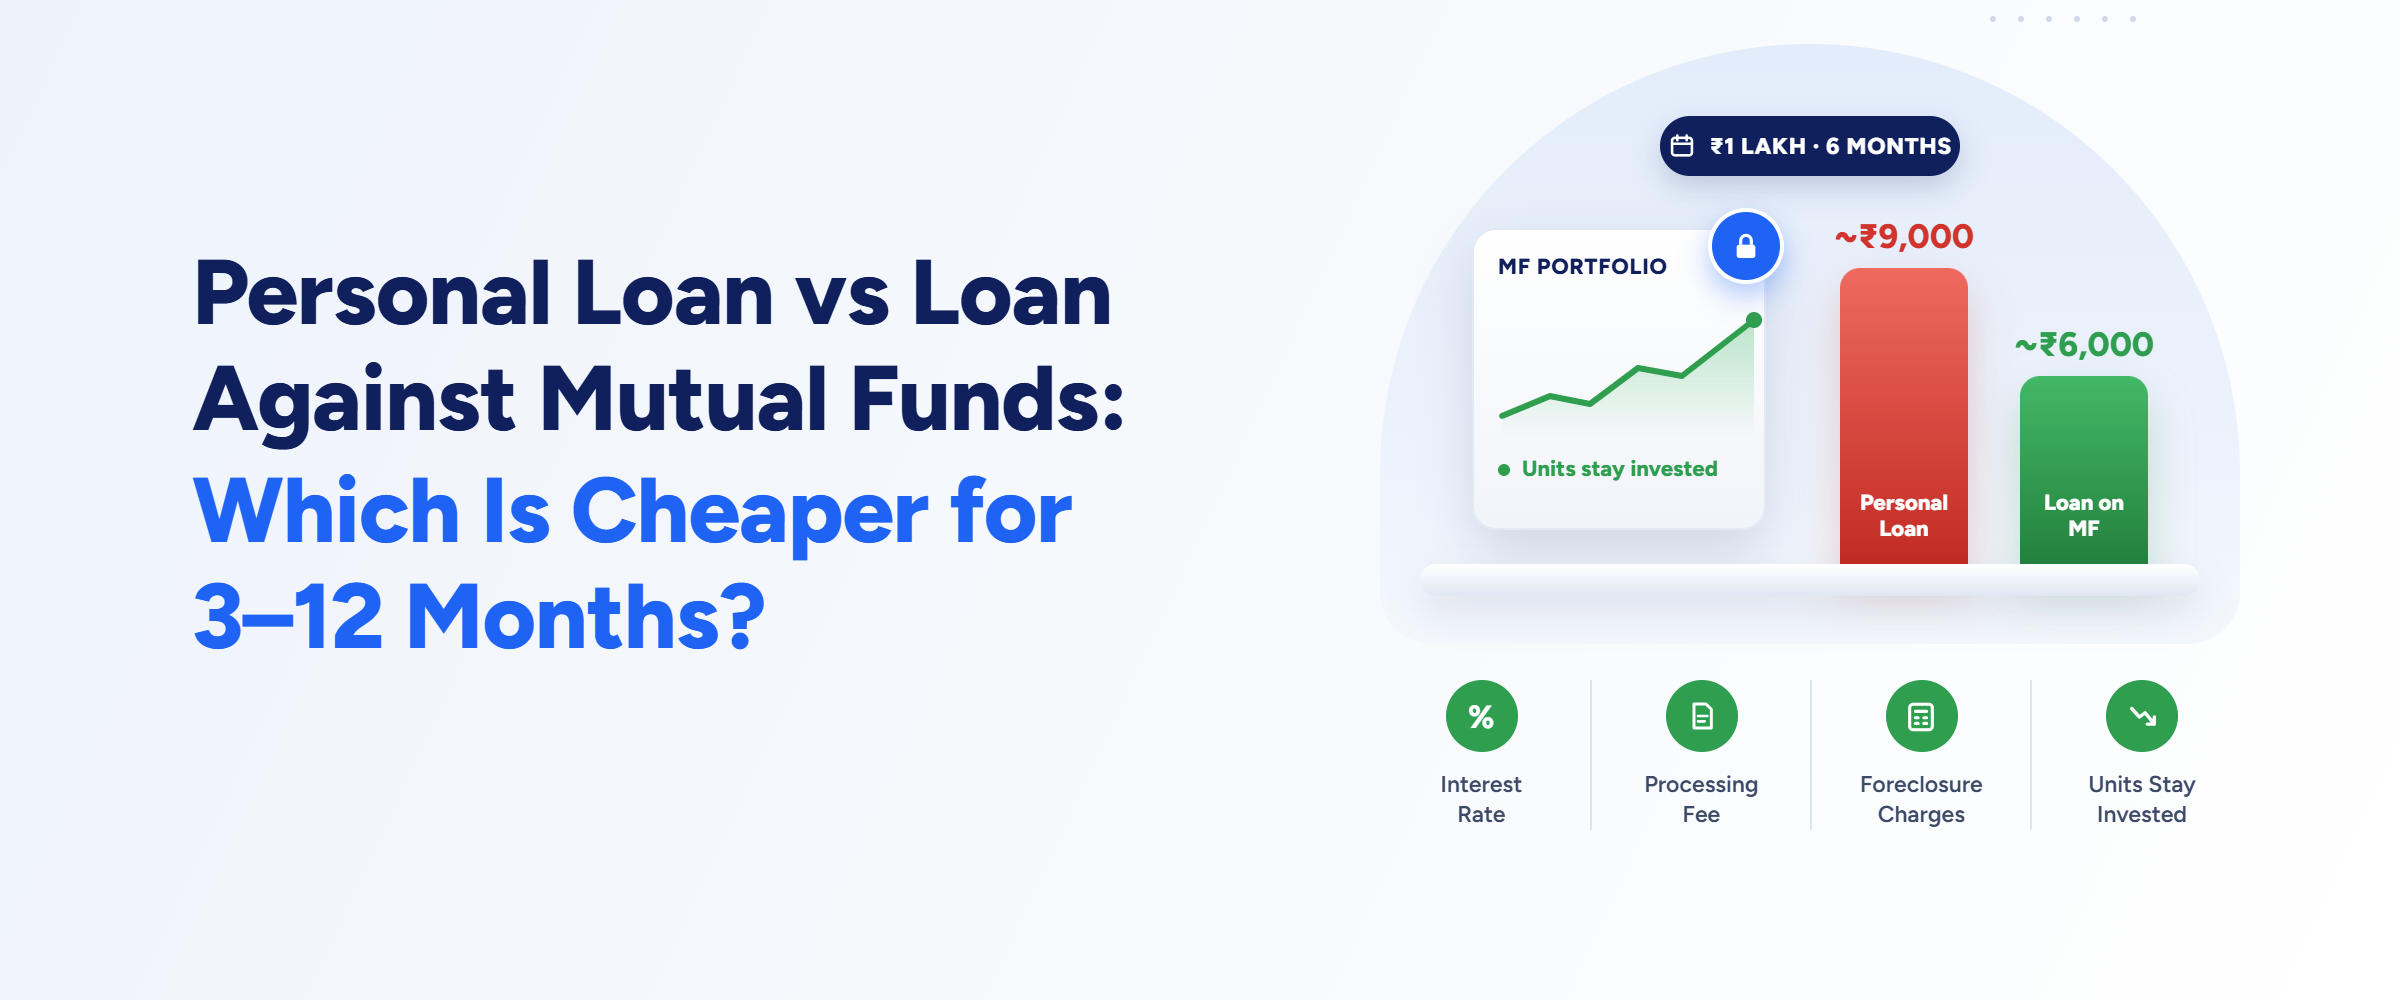
You need funds for a few months, maybe to cover a short-term gap, an upcoming expense, or a temporary shortfall. You have mutual fund investments sitting untouched, and you're wondering: should you pledge them for a loan, or just take a straightforward personal loan and leave your investments alone?
For short-tenure needs specifically, the 3-to-12-month range, this comparison often tilts in a direction many borrowers don't expect. Let's break down the real numbers.
The Core Difference: Unsecured vs Securities-Backed
A personal loan is unsecured, no collateral required, priced based on your income, CIBIL score, and overall credit profile.
A Loan Against Mutual Funds (LAMF) is a securities-backed loan, you pledge your mutual fund units as collateral (via a lien, without selling them), and the lender extends credit based on the value of those units.
| Factor | Personal Loan | Loan Against Mutual Funds (LAMF) |
|---|---|---|
| Collateral | None | Mutual fund units (pledged, not sold) |
| Typical interest rate | Higher | Generally lower |
| Structure | Fixed EMI over a set tenure | Often an overdraft, interest charged only on amount used |
| Speed | Days | Often same-day to a few hours, if fully digital |
| Impact on existing investments | None | Units are pledged (locked), but remain invested and continue earning |
1. LAMF Interest Rate in India – What to Expect
This is where LAMF often has a clear advantage for short-term needs.
Since the loan is fully secured by your mutual fund units, lenders can offer meaningfully lower interest rates compared to unsecured personal loans. As a general market reference:
| Loan Type | Typical Interest Rate Range (Illustrative) |
|---|---|
| Personal loan (unsecured) | Generally higher, varies significantly by credit profile |
| LAMF against equity mutual funds | Often in a noticeably lower range, given the secured structure |
| LAMF against debt mutual funds | Can be marginally lower still, since debt funds are considered less volatile collateral |
Why LAMF is cheaper: the lender's risk is significantly reduced, since they hold a liquid, easily valued asset as security, unlike an unsecured personal loan, where the lender is relying entirely on your creditworthiness with no fallback asset.
2. How Pledged Mutual Funds Loans Actually Work
Understanding the mechanics helps clarify why this product is particularly well-suited to short-term needs.
This overdraft-style structure is a significant advantage for short-term needs, since you're not locked into a fixed EMI schedule or paying interest on funds you haven't actually used.
3. Unsecured vs Securities-Backed Loan – The Tradeoffs Beyond Cost
Cost isn't the only factor worth weighing. Each structure comes with its own set of practical tradeoffs.
Personal loan advantages:
LAMF advantages:
LAMF risks to be aware of:
4. Emergency Funds Without Selling Your SIP
This is one of the most compelling reasons investors increasingly consider LAMF over redeeming investments during a short-term cash need.
The problem with selling to raise emergency funds:
How LAMF avoids this:
This makes LAMF a genuinely different proposition from simply "using your investments for an emergency", it lets you access liquidity without disrupting your long-term financial plan.
Loan Against Shares vs Personal Loan: A Related Comparison
If you hold listed shares rather than (or in addition to) mutual funds, a similar Loan Against Securities (LAS) structure applies, following broadly the same principles as LAMF, collateral pledged via demat account, overdraft-style drawdown, and interest charged only on utilised funds.
| Factor | Loan Against Shares | Loan Against Mutual Funds |
|---|---|---|
| Collateral | Listed equity shares (demat) | Mutual fund units (demat or RTA-held) |
| Typical LTV | Generally lower than debt MF (due to higher volatility) | Higher for debt funds, moderate for equity funds |
| Process | Pledge via demat account/broker | Pledge via RTA (CAMS/KFintech) or NSDL/CDSL |
The underlying logic is the same across both: pledge an existing investment, avoid selling it, and access funds at a lower cost than an unsecured loan, provided you're comfortable with the specific asset's volatility and the lender's revaluation terms.
Worked Example: 6-Month Need, Two Options
Scenario: Priya needs ₹3,00,000 for 6 months to cover a short-term expense. She holds mutual fund investments worth approximately ₹6,00,000 and has a stable salaried income.
Option A: Personal Loan — Fixed EMI over a chosen tenure (say, 6 months), interest calculated on the full disbursed amount from day one. Total interest cost is based on the full loan amount for the full 6 months, per the loan's fixed structure.
Option B: LAMF (Overdraft Structure) — Interest charged only on the amount actually utilised, and only for the days it's utilised. If Priya draws ₹3,00,000 but repays part of it early (say, at the 4-month mark), she only pays interest for the actual utilisation period on that portion, a flexibility a fixed-EMI personal loan doesn't offer.
Illustrative cost comparison (approximate, for a 6-month full utilisation period):
| Personal Loan | LAMF | |
|---|---|---|
| Approximate interest rate (illustrative) | Higher end of typical personal loan range | Meaningfully lower, secured-loan range |
| Structure | Fixed EMI, full amount for full tenure | Overdraft, interest only on used amount/days |
| Flexibility to reduce cost with early repayment | Limited (may involve prepayment considerations) | High, repaying early directly reduces interest cost |
For a genuinely short 3–12 month need, LAMF's combination of a lower base rate and interest-only-on-usage structure often makes it the more cost-effective choice, provided you have sufficient eligible mutual fund holdings to pledge.
Common Mistakes Borrowers Make
Expert Tips for Choosing Between the Two
Compare Your Short-Term Funding Options
Check your personal loan eligibility on IndiaLends and compare offers across lenders, so you can weigh the real cost against alternatives like LAMF before deciding.
Check Your Personal Loan Eligibility Now
Conclusion
For short-term needs in the 3-to-12-month range, a loan against mutual funds often works out cheaper than a personal loan, thanks to its secured structure and interest-only-on-usage design, provided you already hold sufficient eligible investments. A personal loan remains the more universally accessible option, requiring no existing portfolio, but typically comes at a meaningfully higher cost. The right choice depends on what you currently hold and how comfortable you are with the (generally manageable) risk of a margin call on pledged investments.
Related reading: Bonus in the Bank: Prepay the Personal Loan or Keep the EMI Running?, Two Personal Loans at Once: When Stacking Turns Into a Trap, and How to Compare Loan Offers Beyond the Interest Rate.

Scan this QR Code


Latest Articles
Pre-Approved Personal Loan Offers: How to Read the Real Rate
09 Oct 2026
Personal Loan After Credit Card Settlement: Is It Possible?
09 Oct 2026
Account Aggregator Personal Loans: What Lenders Read Beyond Your Salary Slip
08 Oct 2026
Salary Overdraft vs Personal Loan: Which One Should You Use?
08 Oct 2026
Can I Take Two Personal Loans at the Same Time? Risks Explained
08 Oct 2026
Relevant Articles
Pre-Approved Personal Loan Offers: How to Read the Real Rate
09 Oct 2026
Personal Loan After Credit Card Settlement: Is It Possible?
09 Oct 2026
Account Aggregator Personal Loans: What Lenders Read Beyond Your Salary Slip
08 Oct 2026
Salary Overdraft vs Personal Loan: Which One Should You Use?
08 Oct 2026
Can I Take Two Personal Loans at the Same Time? Risks Explained
08 Oct 2026
FAQ’s
Generally, yes. Since LAMF is secured by your mutual fund units, lenders typically offer meaningfully lower interest rates compared to unsecured personal loans, and the overdraft structure means you only pay interest on the amount actually used.
No. Your units remain invested in your name and continue to earn returns (or fluctuate with the market) while pledged. A lien is simply marked on them, preventing redemption or transfer until the loan is repaid and the pledge is released.
If the value of equity-backed pledged funds falls significantly, the lender may ask you to pledge additional units or repay part of the loan to restore the required loan-to-value ratio, similar to a margin call.
Yes, and this is one of LAMF's key advantages, it lets you access funds without selling your investments, avoiding potential capital gains tax and preserving the long-term compounding benefit of your SIP.
Yes. LAMF is only available if you hold sufficient eligible mutual fund units to pledge. Without existing investments, a personal loan remains the accessible option for most borrowers.
 URL copied to clipboard successfully !
Download the IndiaLends App Now
Scan this QR code to download the app