Loans 

Credit Card
IndiaLends App is available in
Account Aggregator Personal Loans: What Lenders Read Beyond Your Salary Slip
Applying for a personal loan used to mean scanning salary slips, downloading months of bank statements as PDFs, and uploading them one by one. Increasingly, that entire process is being replaced by a single consent screen: "Share your financial data via Account Aggregator?"
If you've seen this during a recent loan application and wondered exactly what you're agreeing to share, you're not alone. Understanding what Account Aggregator (AA) data actually contains, and how lenders use it, can help you make sense of a process that's becoming the default way personal loans get assessed in India.
What Is the Account Aggregator Framework?
The Account Aggregator framework is an RBI-regulated system that allows you to securely share your financial data, bank account information, investment details, insurance data, and more, directly from the source institution to a lender (or any other financial service provider), with your explicit, purpose-specific, time-bound consent.
Crucially, the Account Aggregator itself never actually sees, reads, or stores your data, it functions purely as a secure, consent-managing "pipe" that moves encrypted information from the institution holding it (like your bank) to the institution requesting it (like a lender assessing your loan application). This is often referred to as the data-blind principle, and it's central to how the framework maintains your privacy even while enabling faster, digital data sharing.
1. RBI Account Aggregator Lending – How It Fits the Loan Process
Instead of manually collecting and uploading bank statements, salary slips, and investment proofs, an AA-enabled loan application allows you to:
This entire process typically happens within minutes, compared to the days it might take to gather and verify physical or manually uploaded documents.
2. Bank Statement Alternative via AA – What's Actually Different
A common misconception is that AA data is somehow different or additional information beyond what a traditional bank statement would show. In reality, for bank account data specifically, AA largely delivers the same underlying information your bank statement already contains, transaction history, account balances, and credit/debit patterns, just through a faster, digital, consent-based channel rather than a manually uploaded PDF.
| Traditional Method | Account Aggregator Method |
|---|---|
| Download bank statement PDF, upload manually | Data fetched directly and securely via consent |
| Lender manually reviews/extracts data from PDF | Data arrives in a structured, analysis-ready format |
| Processing time: hours to days | Processing time: often minutes |
| Risk of tampered/edited PDF statements | Data sourced directly from the bank, reducing fraud risk |
The genuine value-add isn't new categories of hidden data, it's speed, accuracy, and a reduced risk of document manipulation, since the data comes directly from the source institution rather than a file you've uploaded yourself.
3. Cash Flow Underwriting for Personal Loans – What Lenders Actually Analyse
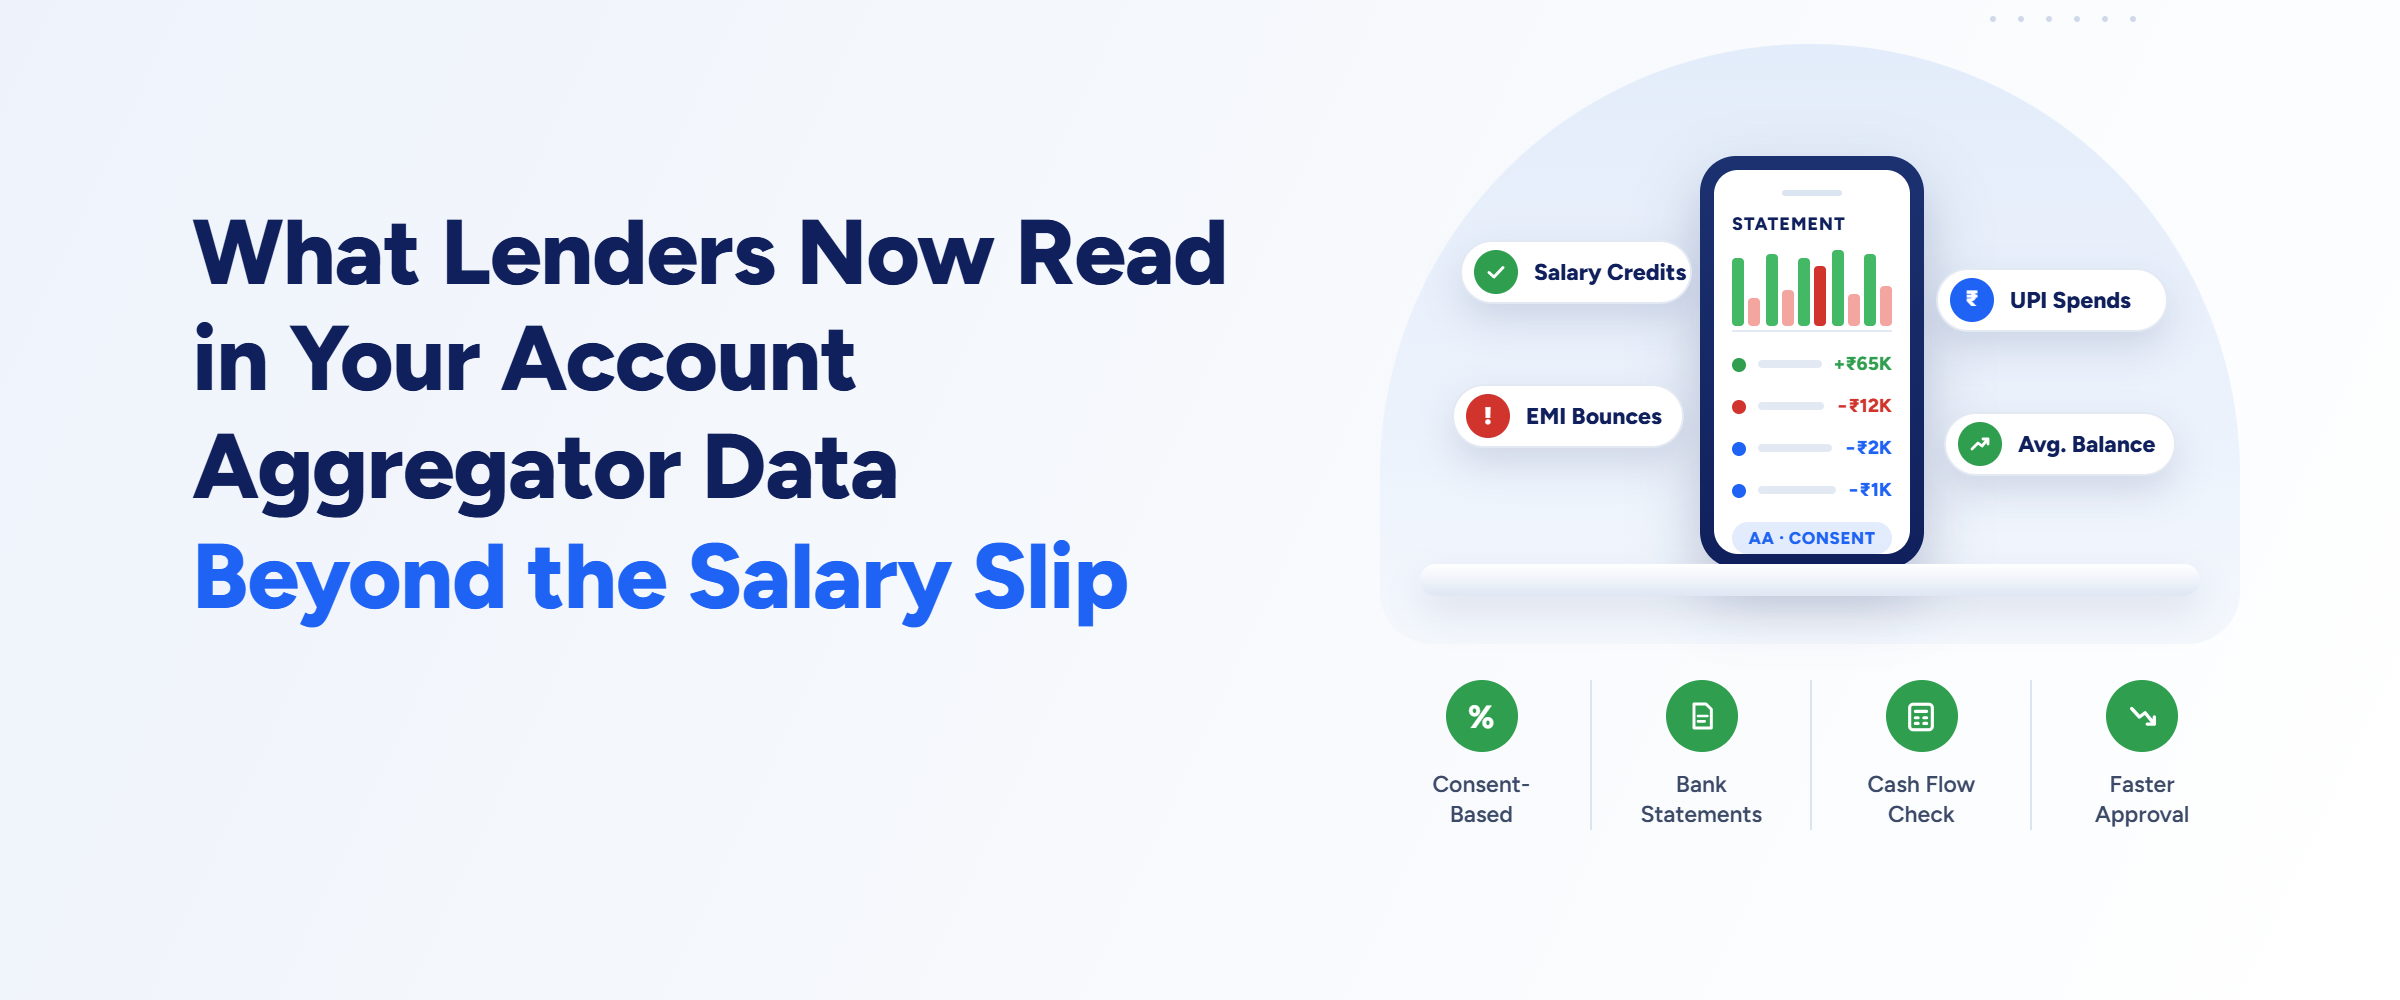
This is where the "beyond the salary slip" part of the story comes in. With structured, comprehensive transaction data readily available through AA, lenders increasingly build their assessment around cash flow underwriting, a more holistic view of your financial behaviour, not just a snapshot of your declared income.
Specifically, lenders commonly analyse:
Why this matters for you: cash flow underwriting can actually work in your favour if your income is a little unconventional (for instance, if you have side income, or your salary structure is unusual) but your overall financial behaviour is genuinely healthy, something a single salary slip alone might not fully capture.
4. Consent for Account Aggregator – What You're Actually Agreeing To
Understanding your consent rights is important, since this entire framework is built on the principle that you remain in control of what's shared, with whom, and for how long.
Key aspects of AA consent:
Practical tip: always read the consent screen carefully before approving, it will specify exactly what data (which accounts, what time period) is being requested and for what stated purpose, giving you the opportunity to decline or adjust the scope if something seems broader than expected.
5. Bounced EMI in AA Data – A Detail Worth Knowing
Here's a specific, practical detail many borrowers don't think about until it affects them: if your linked bank account data shows bounced EMI payments, failed auto-debits, or insufficient balance instances, this will be visible to the lender reviewing your AA-shared transaction history, just as it would be visible in a traditional bank statement.
This isn't a new or hidden risk introduced by AA, it's simply that the same information that was always present in your bank statement is now being reviewed faster and more comprehensively.
What this means practically:
Example: How AA Data Changes a Loan Application
Case 1: Traditional Process — Vikram applies for a personal loan the conventional way, downloading and uploading 6 months of bank statements as PDFs, along with his salary slips. The lender's team manually reviews these documents, a process that takes 2–3 days before a decision is communicated.
Case 2: Account Aggregator Process — Meera applies for a similar loan through a lender offering AA-based assessment. She links her salary account via her AA app, reviews and approves the specific consent request (covering the last 6 months, for loan eligibility purposes), and the lender receives her transaction data within minutes. Her application, including cash flow-based eligibility assessment, is processed same-day.
Both borrowers' underlying financial data is essentially the same information, the difference lies entirely in speed, format, and how comprehensively the lender can analyse it.
Common Mistakes Borrowers Make
Expert Tips for Navigating AA-Based Loan Applications
Apply for a Personal Loan With a Faster, Transparent Process
Check your personal loan eligibility on IndiaLends and experience a streamlined application process, with full clarity on what data is used and why, every step of the way.
Check Your Personal Loan Eligibility Now
Conclusion
Account Aggregator isn't introducing some new, hidden layer of scrutiny into your personal loan application, it's largely digitising and accelerating access to the same financial information lenders have always reviewed, just faster and with stronger consent controls than manually uploaded documents ever offered. What's genuinely new is how comprehensively and quickly lenders can now build a cash flow-based picture of your financial behaviour, which can work in your favour if your finances are genuinely healthy, even if your income doesn't fit a conventional, single-salary-slip mould.
Related reading: Lenders Don't Count "Cash Sales": How They Rebuild Your Real Turnover, The Cooling-Off Period on Digital Personal Loans, Personal Loan Co-Applicant: Benefits, Risks, and Impact on Approval, and Should You Take a Personal Loan During Your Notice Period?

Scan this QR Code


Latest Articles
Salary Overdraft vs Personal Loan: Which One Should You Use?
08 Oct 2026
Loan Against Mutual Funds vs Personal Loan: Which Is Cheaper?
08 Oct 2026
Can I Take Two Personal Loans at the Same Time? Risks Explained
08 Oct 2026
Merchant Cash Advance vs Business Loan: The Real Cost Comparison
30 Sep 2026
Business Loan Turnover Calculation: Why Cash Sales Don't Count
30 Sep 2026
Relevant Articles
Salary Overdraft vs Personal Loan: Which One Should You Use?
08 Oct 2026
Loan Against Mutual Funds vs Personal Loan: Which Is Cheaper?
08 Oct 2026
Can I Take Two Personal Loans at the Same Time? Risks Explained
08 Oct 2026
Should I Prepay My Personal Loan? Bonus vs EMI Decision Guide
30 Sep 2026
RBI Cooling-Off Period on Personal Loans: What You Can Actually Undo
18 Sep 2026
FAQ’s
Account Aggregator is an RBI-regulated framework that lets you securely share your financial data, like bank statements, directly with a lender, with your explicit consent, replacing manual document upload with a faster, digital process.
No. The AA acts as a data-blind intermediary, it facilitates the secure transfer of your data from your bank (or other institution) to the lender, based on your consent, without reading, storing, or using the data itself.
For bank account data specifically, it's largely the same underlying transaction history and balance information your bank statement already contains, the key difference is the speed, structured format, and consent-based, direct-from-source delivery.
Yes. Just as this information would appear in a traditional bank statement, any bounced payments or irregular transactions in your linked account history remain visible to a lender reviewing your AA-shared data for the consented period.
Yes, you can revoke consent at any time through your AA app, which stops any future data sharing. However, this doesn't undo data that has already been legitimately shared under a valid, prior consent.
 URL copied to clipboard successfully !
Download the IndiaLends App Now
Scan this QR code to download the app