Loans 

Credit Card
IndiaLends App is available in
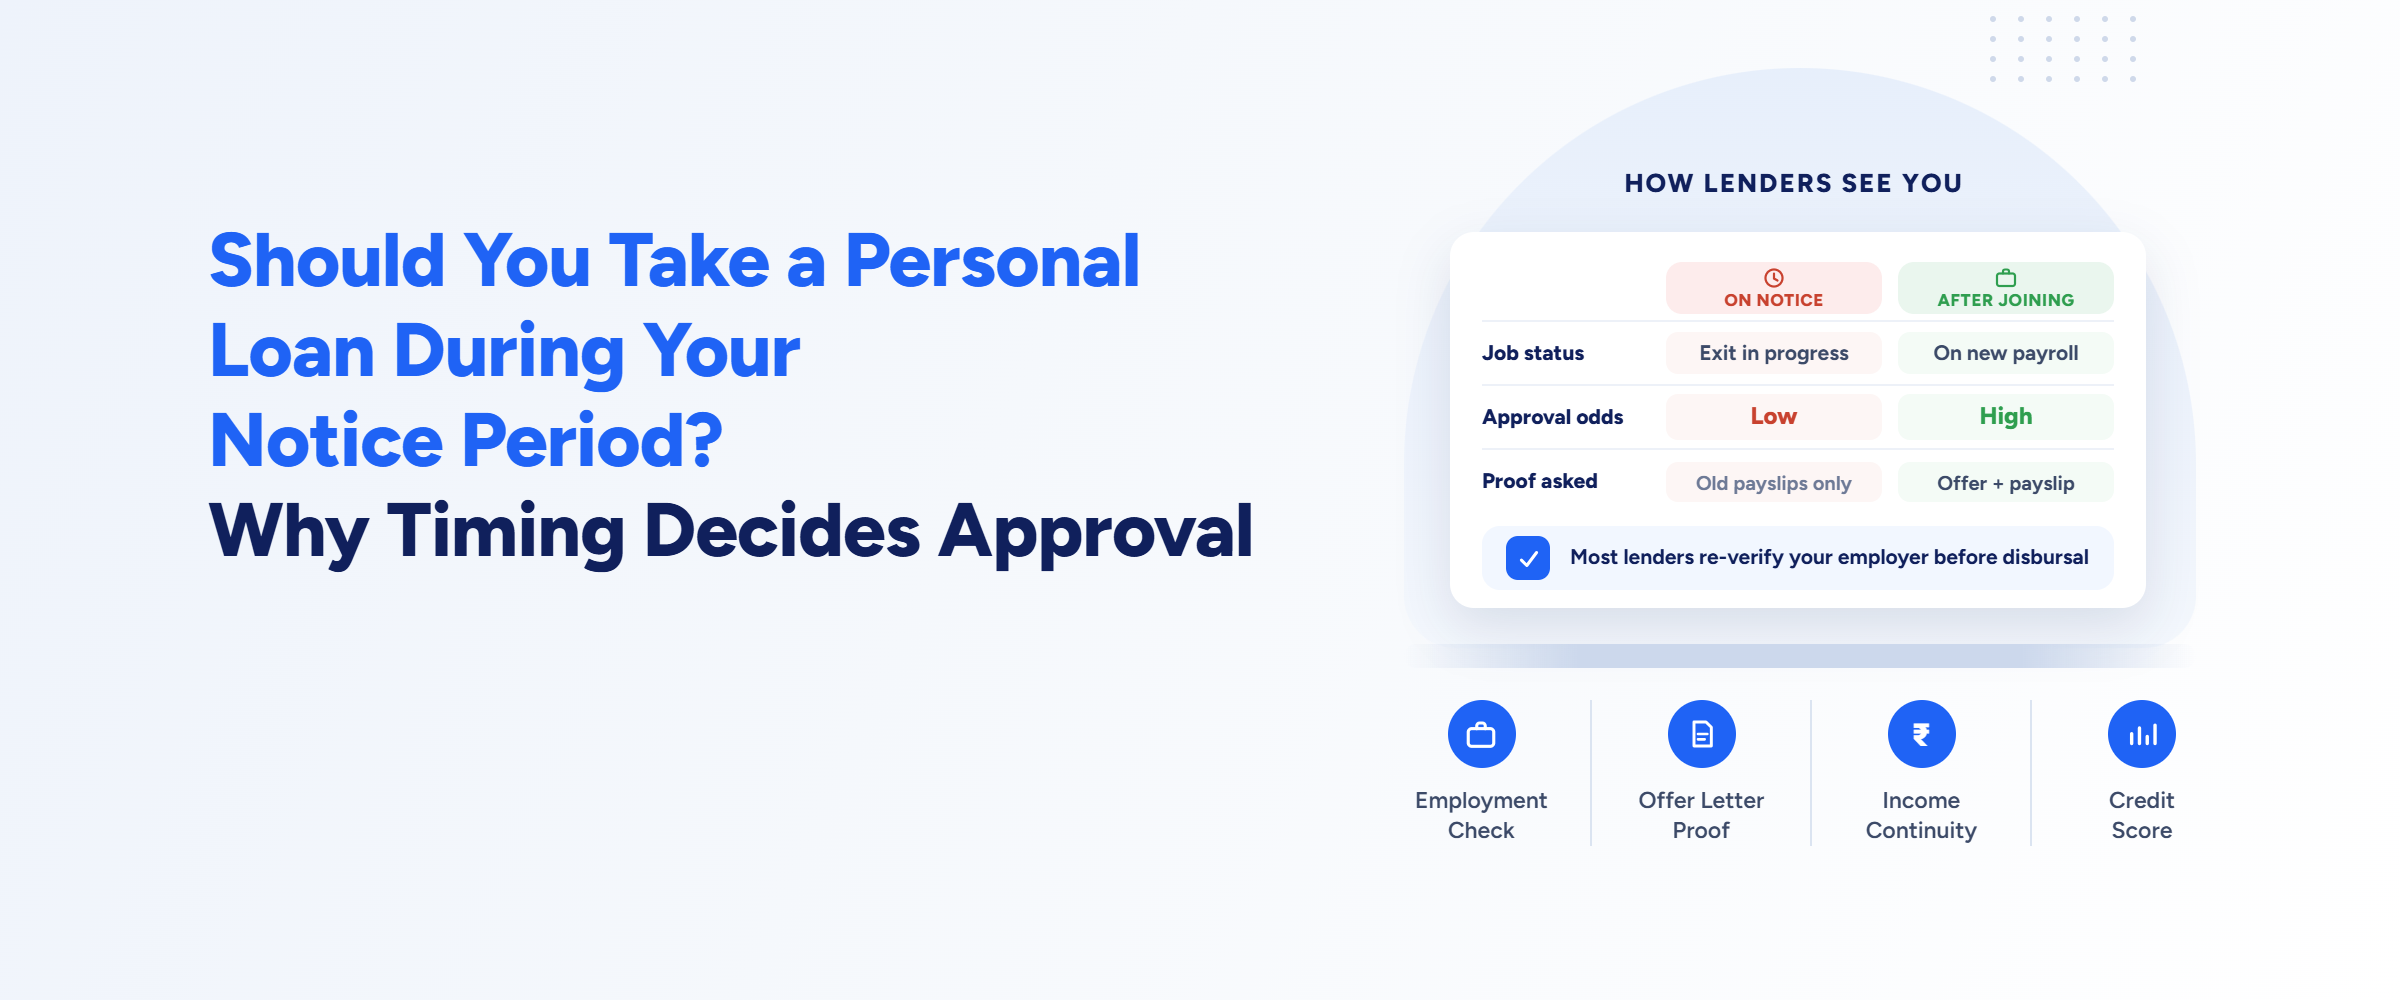
Should You Take a Personal Loan During Your Notice Period?
You've just resigned, you're serving your notice period, and now you need funds, maybe to cover relocation costs for a new job, clear a pending expense, or simply bridge a gap before your next salary lands. Naturally, you consider a personal loan.
But here's the catch: your employment status is about to change, and lenders care deeply about employment stability when assessing loan eligibility. Does that mean you should avoid applying altogether? Not necessarily, but you do need to understand exactly how lenders view this situation before you apply.
Why Your Notice Period Matters to a Lender
A personal loan is unsecured, there's no collateral backing it. This means lenders lean almost entirely on your income stability and repayment capacity to assess risk. Your notice period sits right in the middle of a transition that directly affects both.
From a lender's perspective, a borrower currently serving notice raises a specific question: will this person still have a stable, verifiable income by the time the loan is disbursed and EMIs begin?
This is why notice period status can influence approval, loan amount, and even processing time, sometimes significantly.
1. What Changes During a Notice Period
Once you resign, several things shift that are directly relevant to a loan application:
None of this means you're ineligible, it simply means lenders apply extra scrutiny during this window.
2. Lender Policy on Notice Period in India – What Varies
There's no single, universal rule across all banks and NBFCs. Lender policy on notice period in India varies meaningfully:
| Lender Approach | What It Typically Means for You |
|---|---|
| Standard salaried eligibility check, no special notice period clause | Approval depends mainly on your current salary credits and CIBIL score, with limited scrutiny of notice period status |
| Explicit notice period disclosure required | You must inform the lender if you're serving notice; non-disclosure can affect approval or lead to issues later |
| Conditional approval pending employment confirmation | Lender may delay final disbursal until your new employment or continued salary credit is confirmed |
| Stricter policy, decline during active notice period | Some conservative lenders may simply decline applications from borrowers currently serving notice, regardless of profile strength |
Practical takeaway: Always check directly with your chosen lender rather than assuming any one policy applies universally, this single factor can significantly affect whether, and how, your application is processed.
3. Salary Credit for Personal Loan – Why the Pattern Matters More Than the Timing
Lenders don't just check that you're currently salaried, they check your salary credit pattern over recent months (commonly the last 3-6 months of bank statements). A consistent, on-time salary credit history strengthens your application significantly, regardless of your current notice period status.
Why this matters specifically during a notice period: if your salary credits have been regular and on-time up to your application date, this history still counts in your favour, lenders are assessing your demonstrated repayment capacity, not just a snapshot of your current employment status.
However, if your notice period means you won't receive your usual salary before resignation (for instance, if you're on unpaid leave during part of your notice), this can weaken your application, since it directly affects your near-term repayment ability.
Applying While Still Employed (Before Resigning)
If you're planning to resign but haven't yet, and you know you'll need a loan, this is generally the safer window to apply:
Applying During an Active Notice Period
This is where things get more nuanced:
Applying After Resignation, Before a New Job Starts
This is generally the most difficult window:
Personal Loan Job Switch: A Common, Related Scenario
Many borrowers aren't just resigning, they're actively switching jobs, often with a new offer already in hand. This is meaningfully different from resigning without a confirmed next step, and lenders often treat it more favourably:
Personal Loan Disbursal After Relieving Letter: Why Some Lenders Wait
In certain cases, particularly for larger loan amounts, or with more conservative lenders, the lender may choose to hold final disbursal until after you've received your relieving letter and joined your new employer, especially if:
This isn't universal, but it's worth knowing that some lenders build in this kind of safeguard, which can extend your loan's overall processing timeline if you're mid-transition.
Example: Two Borrowers, Two Outcomes
Case 1: Ankita, Applied Before Resigning — Ankita knew she needed ₹2,50,000 for a personal expense and planned to switch jobs in the coming months. She applied for a personal loan while still employed at her current company, with 8 months of consistent salary credits on record. Her loan was approved and disbursed within 3 days, well before she submitted her resignation the following month.
Case 2: Rohit, Applied Mid-Notice-Period — Rohit resigned and, a week into his notice period, applied for a ₹3,00,000 personal loan to cover relocation costs for his new job. He disclosed his notice period status and provided his new employer's offer letter. The lender processed his application but held disbursal until he could confirm his new joining date and salary structure, extending his timeline by about a week compared to a standard application.
Both eventually got approved, but Ankita's timing avoided the additional scrutiny Rohit had to work through.
Common Mistakes Borrowers Make
Expert Tips for Applying Around a Notice Period
Check Your Personal Loan Eligibility Today
Check your personal loan eligibility on IndiaLends and compare offers from multiple banks and NBFCs with clear guidance on documentation, whatever stage of your career transition you're in.
Check Your Personal Loan Eligibility Now
Conclusion
Applying for a personal loan during your notice period isn't off-limits, but it does require more awareness than applying under stable, ongoing employment. The safest approach is applying before you resign, if you can plan ahead; the next best approach is honest disclosure and having your new job details ready if you're already mid-transition. Lender policies vary enough that a quick, direct conversation with your chosen lender before applying can save you both time and unnecessary complications.
Related reading: Personal Loan Co-Applicant: Benefits, Risks, and Impact on Approval and Bank vs NBFC Loan: How to Choose the Right Offer.

Scan this QR Code


Latest Articles
RBI Cooling-Off Period on Personal Loans: What You Can Actually Undo
18 Sep 2026
Gold Loan for Business Working Capital: Cheaper Than a Business Loan?
11 Sep 2026
Gold Coin vs Jewellery Loan: What Lenders Will and Won't Accept
11 Sep 2026
Online Gold Loan vs NBFC Branch: Rate, Purity Test & Vault Safety
11 Sep 2026
Gold Loan When Gold Prices Fall: Margin Calls & Top-Up Rules Explained
11 Sep 2026
Relevant Articles
RBI Cooling-Off Period on Personal Loans: What You Can Actually Undo
18 Sep 2026
Why Do Two Lenders Offer Different Interest Rates to the Same Borrower?
03 Sep 2026
How to Compare Loan Offers Beyond the Interest Rate
03 Sep 2026
Bank vs NBFC Loan: How to Choose the Right Offer in 2026
03 Sep 2026
Personal Loan Co-Applicant: Benefits, Risks & Impact on Approval
03 Sep 2026
FAQ’s
Yes, in many cases, though it depends on the specific lender's policy. Some process applications normally if your salary credits continue as usual, while others may ask for additional documentation like a new employer's offer letter, or delay disbursal until your employment is confirmed.
It can, particularly if you apply after resigning without a confirmed new job. Lenders rely heavily on stable, verifiable income, so an active employment gap can make approval more difficult compared to applying while still employed.
Yes, if asked directly, it's important to disclose this honestly. Non-disclosure can be treated as a discrepancy if discovered during verification, which may affect your application more than transparent disclosure would have.
Generally, applying before resigning, while your employment and salary credit history are stable and current, is the smoother option. Applying after resignation, especially without a confirmed new job, is typically the more difficult scenario.
It can be, particularly for larger loan amounts or with more conservative lenders, who may want to confirm your new employment and salary structure before releasing funds. This isn't universal, so it's worth asking your specific lender about their process.
 URL copied to clipboard successfully !
Download the IndiaLends App Now
Scan this QR code to download the app